


Costing Steelwork is a series from BCSA, Steel for Life and Aecom that provides guidance on costing structural steelwork. This quarter provides a construction market update by Dr Michael Sansom based on recent CPA forecasts, and data on prices and costs from Pablo Cristi Worm of Aecom, along with guidance on fire protection responsibilities
Click here to read the full costing report
The summer outlook is more pessimistic than the spring forecast, with total construction output now predicted to drop 3.3% in 2026, compared with a 2.5% drop forecast in spring. Forecast growth of 1.2% in 2027 is unchanged but from a lower base. This deterioration reflects weaker-than-expected activity in the first half of 2026, alongside increasing construction product, energy and financing costs.
The main downward revisions are in housing, commercial and industrial. Commercial output is now forecast to fall 4.9% in 2026, compared with a 3.7% fall previously, while industrial has been dramatically revised from a 2.4% rise to a 3.3% fall. Infrastructure remains relatively resilient, with the forecast of a 3.2% rise unchanged for 2026, although 2027 has been marginally reduced from a 3.4% to a 3.2% rise.
The underlying message is that inflation may preserve the cash value of construction while reducing the physical volume delivered, particularly for infrastructure and other large, materials-intensive projects.
Following the weather-affected Q1, activity between March and June was a considerable improvement; however, concerns remain over the impacts of the Middle East conflict. Rising oil, energy, commodity and construction-product prices are expected to feed through into construction costs, alongside higher financing costs, leading to investor uncertainty about committing to new projects. Further tax rises or public spending cuts in the 2026 or 2027 Budgets are also a risk; the government’s 50% tariff on imported steel products since 1 July is likely to increase costs too.
Construction-specific constraints include continuing contractor insolvencies, Building Safety Regulator delays, skill shortages and concerns about the reliability of ONS construction data used for CPA forecasts.
Commercial development remains tricky, particularly for large new-build offices and major back-to-frame refurbishments. Smaller, high-end refurbishment and fit-out remains comparatively strong, but high financing and construction costs are making clients increasingly cautious in committing to major schemes.
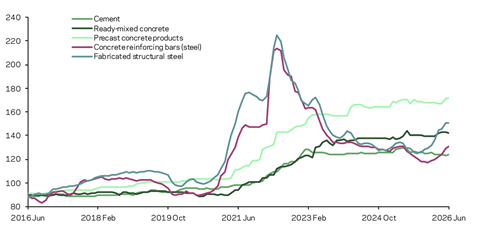
Figure 1: Monthly construction material price indices
Price indices of construction materials 2015=100. Source Department for Business and Trade
The office market is key for structural steelwork. CPA predicts decision-making on many large office schemes to stall through 2026 and much of 2027. Office output is forecast to fall 7% in 2026, compared with a 4% fall previously forecast. There is nevertheless a substantial pipeline of London and regional schemes that could eventually support recovery.
Commercial construction cost inflation is expected to accelerate in H2 2026, adding to cost increases already built into projects when investment decisions were first made. Combined with higher borrowing costs, this is worsening viability and may delay large projects.
Industrial output shows the biggest deterioration since spring. Traditional steel-intensive markets like warehouses and factories remain weak, with activity increasingly concentrated in smaller schemes. The exceptions are data centres, giga-factories and major one-off industrial investments, including Tata Steel’s Port Talbot EAF project. However, these large projects are not expected to offset the weakness elsewhere. Data centres remain one of the strongest opportunities for steel construction, but their growth is constrained by planning, grid capacity and connection delays. Data-centre activity is expected to increase from 2027, however, subject to grid connections.
Accelerating cost inflation is identified as one of the main risks to factories, warehouses and data centres because it can undermine final investment decisions and project viability. This is particularly important for large, privately financed capital projects.
Infrastructure output is forecast to grow 3.2% annually from 2026 to 2028. Growth is concentrated in electricity generation and transmission, water and sewerage, supported by projects such as Hinkley Point C, Sizewell C and National Grid investment.
The picture is weaker for transport. Rail activity is constrained by the HS2 reset, while roads face reduced investment and possible further cancellations as government capital spending is reprioritised.
Construction product inflation will particularly impact infrastructure because projects tend to use large quantities of energy-intensive materials. Rising materials and energy costs could reduce private-sector project viability and quickly erode the relatively limited contingency in publicly funded projects.
Figure 2: Tender price inflation, Aecom Tender Price Index, 2019=100
| Forecast | ||||||
|---|---|---|---|---|---|---|
| Quarter | 2023 | 2024 | 2025 | 2026 | 2027 | 2028 |
| 1 | 122.4 | 122.7 | 126.3 | 130.7 | 135.8 | 139.8 |
| 2 | 123.4 | 123.7 | 127.5 | 131.7 | 136.8 | 141.1 |
| 3 | 123.5 | 124.7 | 128.5 | 133.0 | 137.7 | 142.4 |
| 4 | 122.5 | 125.7 | 129.4 | 134.5 | 138.5 | 143.8 |
Implications for structural steel
For the structural steelwork sector, the forecast is mixed but clearly weaker in the short term.
The traditional high-volume steel markets of large offices, warehouses and factories are subdued, which is likely to keep competitive pressure on fabricators through 2026. Conversely, the strongest areas of construction are also relatively steel-intensive: data centres, energy generation and transmission, water infrastructure, giga-factories and eventually the pipeline of major grade A commercial developments.
A particularly important new risk is steel pricing itself; a consequence of the UK’s 50% tariff on steel imported outside the reduced quotas from 1 July 2026. Although structural steel prices have risen in 2026, any further impacts of the new quotas and tariffs are only likely to become apparent towards the end of 2026.
Overall, the outlook for structural steel is weaker than the headline construction forecast suggests in 2026, because commercial and traditional industrial buildings are disproportionately important steel markets. The medium-term picture is more positive, with demand shifting towards energy infrastructure, data centres, advanced manufacturing and later major commercial schemes, but the timing of that recovery is uncertain.
Sourcing cost information
Cost information is generally derived from a variety of sources, including similar projects, market testing and benchmarking. Due to the mix of source information it is important to establish relevance, which is paramount when comparing buildings in size, form and complexity.
Figure 3 represents the costs associated with the structural framing of a building, with a BCIS location factor of 100 expressed as a cost/m² on GIFA. The range of costs represents variances in the key cost drivers. If a building’s frame cost sits outside these ranges, this should act as a prompt to interrogate the design and determine the contributing factors.
The location of a project is a key factor in price determination, and indices are available to enable the adjustment of cost data across different regions. The variances in these indices, such as the BCIS location factors (figure 3), highlight the existence of different market conditions in different regions.
To use the tables:
1. Identify which frame type most closely relates to the project under consideration
2. Select and add the floor type under consideration
3. Add fire protection as required.
For example, for a typical low-rise frame with a composite metal deck floor and 60 minutes’ fire resistance, the overall frame rate (based on the average of each range) would be:
£195.00 + £140.50 + £35.50 = £371.00
The rates should then be adjusted (if necessary) using the BCIS location factors appropriate to the location of the project.
Figure 3: Indicative cost ranges based on gross internal floor area
| TYPE | Base index 100 (£/m2) | Notes |
|
Frames |
||
|
Steel frame to low-rise building |
180-210 |
Steelwork design based on 55kg/m2 |
|
Steel frame to high-rise building |
294-344 |
Steelwork design based on 90kg/m2 |
|
Complex steel frame |
360-420 |
Steelwork design based on 110kg/m2 |
|
Floors |
||
|
Composite floors, metal decking and lightweight concrete topping |
119-162 |
Two-way spanning deck, typical 3m span with concrete topping up to 150mm |
|
Precast concrete composite floor with concrete topping |
148-208 |
Hollowcore precast concrete planks with structural concrete topping spanning between primary steel beams |
|
Fire protection |
||
|
Fire protection to steel columns and beams (60 minutes resistance) |
30-41 |
Factory applied intumescent coating |
|
Fire protection to steel columns and beams (90 minutes resistance) |
47-78 |
Factory applied intumescent coating |
|
Portal frames |
||
|
Large-span single-storey building with low eaves (6-8m) |
116-151 |
Steelwork design based on 35kg/m2 |
|
Large-span single-storey building with high eaves (10-13m) |
141-180 |
Steelwork design based on 45kg/m2 |
Figure 4: BCIS location factors, as at Q3 2026
| Location | BCIS Index | Location | BCIS Index |
|
Central London |
121 |
Nottingham |
102 |
|
Manchester |
103 |
Glasgow |
93 |
|
Birmingham |
94 |
Newcastle |
88 |
|
Liverpool |
101 |
Cardiff |
101 |
|
Leeds |
103 |
Dublin |
90* |
*Aecom index
Steel For Life sponsors
Fire protection responsibilities in steel construction
New guidance from the BCSA aims to clarify who does what
As the UK construction industry adapts to the new regulatory landscape created by the Building Safety Act, one issue has become increasingly important: ensuring everyone involved in a project understands exactly what their responsibilities are.
Since the Grenfell Tower tragedy, regulators have increasingly focused on ensuring that responsibilities are clearly defined and allocated and that duty holders cannot assume others have addressed critical safety issues. The emphasis has moved from simply achieving compliance to demonstrating how compliance has been achieved and who is responsible for each decision.
For the structural steel sector, this sits alongside several other important developments. The implementation of the Building Safety Act, the introduction of the Building Safety Regulator, and greater scrutiny of the “golden thread” of information all require better documentation, improved co-ordination and clearer evidence that regulatory requirements have been satisfied throughout a project’s lifecycle.
To address these requirements, in the context of fire protection of steel-framed buildings, the BCSA has published a good practice guide for fire protection responsibilities in steel construction, available from bcsa.org.uk/resources/fabrication-technical-design/industry-specifications/
The publication focuses on buildings where structural steelwork is protected using intumescent coating systems. While the technical principles of fire protection are well established, the guidance recognises that the industry’s procurement routes have often left uncertainty over who is responsible for critical decisions.
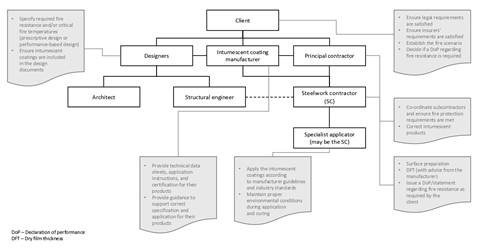
The document proposes a procurement option and establishes the relationships between the various parties:
- The client and their appointed designers are responsible for establishing the fire strategy and defining the performance requirements for the building. These requirements form the basis of the contractual specification and ultimately determine the fire protection that the structural steelwork must achieve.
- The intumescent coating manufacturer has responsibility for providing guidance to support the specification of an appropriate coating system capable of delivering the required fire resistance for the specified steel sections and loading conditions.
- The steelwork contractor must ensure that the specified requirements are properly understood and implemented.
- Finally, the coating applicator remains responsible for the quality of the application process itself, including workmanship, quality assurance and compliance with the manufacturer’s specification.
The diagram below shows the contractual (solid) and functional (dashed line) relationships for the procurement of fire protection for structural steelwork. The diagram is specific to the procurement of intumescent products and other relationships may exist between these parties for other aspects of the project.
Overall, the BCSA guidance represents an important contribution to improving competence and accountability across the steel construction supply chain. By clearly defining the responsibilities of each party, it supports safer procurement practices, better project coordination and improved regulatory compliance. As the UK construction industry continues to adapt to the Building Safety Act, such clarity will become increasingly important in delivering safe, compliant and high-quality buildings.
Figure 1: Guidance on fire protection responsibilities in the procurement of intumescent products for structural steel
Reshaping labour models in construction: employment status, subcontractors and the new right to work regime
The BCSA is hosting a webinar on this subject, presented by Vaughan Hart on 12 October 2026, from 2pm to 3.30pm.
This webinar will explore the different labour models used in the construction sector, including employees, workers, agency labour, self-employed individuals and subcontractors, and examine why employment status is subject to increasing legal and regulatory scrutiny. It will explain the key risks around CIS, agency arrangements and subcontracting, including why contractual labels may not reflect the true working relationship.
The session will also consider agency labour and other supply-chain arrangements, outline the new right to work requirements, and provide practical steps for contractors, HR professionals and managers to review workforce and supply-chain compliance.
To register your attendance, click here.
Costing Steelwork is available at www.steelconstruction.info. The pricing data and rates contained in this article should be used for comparative purposes only and should not be used or relied upon for any other purpose without further discussion with Aecom. Aecom does not owe a duty of care to the reader or accept responsibility for any reliance on the contents of the article.



No comments yet